Takeaways
- Simple, cost-free behaviors, such as returning phone calls promptly, arriving on time and maintaining a clean work area, significantly add value to your business and build client trust.
- Vehicle costs, such as fuel, maintenance, insurance and depreciation, are among your highest expenses and must be factored into your pricing.
- Use a Schedule C form to track profit and loss, and explore strategies to reduce tax burdens, such as contributing to tax-deferred retirement accounts like an IRA.
Learning to shoe horses for a living is not the easiest job to attempt. It can be rewarding if you go about it the right way.
Certainly, the beginning starts with horse handling skills or riding and training experience. Next comes the basics, like learning normal anatomy, conformation and function. Then we progress to hoof trimming and how that affects the horse. Horseshoe selection, fitting and modifications follow, ultimately leading to attaching the shoes and finishing the job. All done, let’s move on to the next horse, right? Not so fast!
Unless you are just shoeing your own horses, now you are running a business either part- or full-time. Beyond the actual physical part of working on horses, what else needs to happen to run a successful business and enjoy a full career in this profession?
There are two other aspects that are essential to success. First, there is the personal aspect of how you conduct yourself, the second is the behind-the-scenes business aspect. Successful farriers practice the following behaviors.
- Return phone calls promptly.
- Plan a reasonable schedule that enables arrival for appointments on time.
- Being prepared for the type of work planned with time, materials and know how.
- Handling horses in a professional manner.
- Explaining to your clients when better management ideas are necessary.
- Cleaning up your work area when finished.
- Working well with trainers and veterinarians.
These practices don’t cost anything; however, they add value to your business.
Running a farrier business has expenses beyond horseshoes and nails. These need to be factored into pricing your services.
“Trying new products on your personal horses might be tax-deductible…”
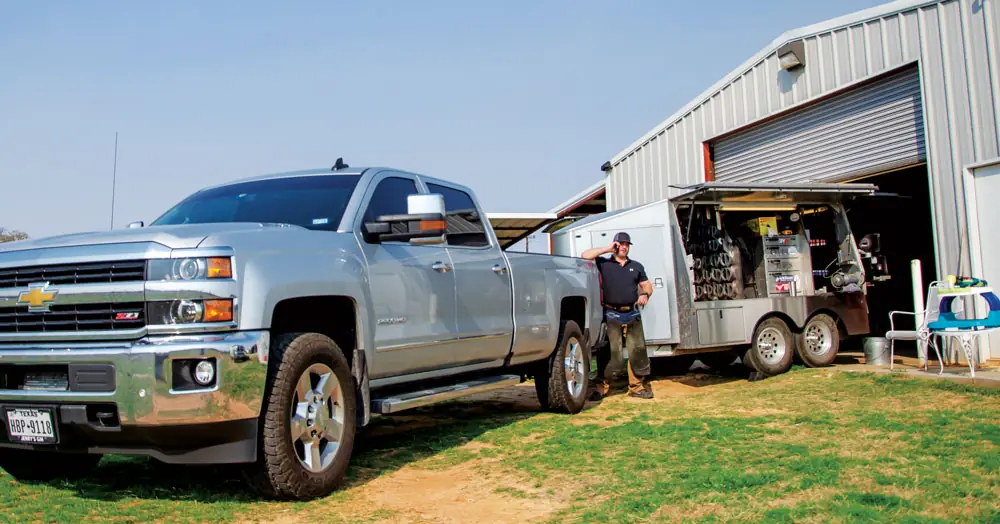
Most farriers offer mobile services, so vehicle expenses are one of your largest costs. Divide these monthly occurring expenses into either your monthly gross or into the number of horses that are trimmed and/or shod per month. These include:
- Actual cost of the vehicle, which transfers to yearly depreciation expenses over the life the truck is used.
- Vehicle insurance.
- Vehicle maintenance and repairs.
- Fuel.
Next comes business expenses, the items that are the glue that organizes you. Again, divide these monthly expenses into the number of horses that are trimmed and/or shod per month.
- Phone.
- Internet.
- Business insurance.
- Business checking account.
- Office supplies, miscellaneous expenses.
- Yearly business expenses include:
- Association membership fees.
- American Farriers Journal and other continuing education subscriptions.
- Travel to clinics, etc.
- Accounting/tax preparation fees.
If you own horses, you might also be able to deduct those expenses as part of your business. You can justify this by keeping accurate records when you are trying new products on them. If you trail ride or compete in events with clients you shoe for, you can justify your horse expenses because you might not have them in your business if you’re not at these events.
Finally, there are your horseshoes, nails, pads, propane and items directly related to shoeing a horse. Since these materials can vary for different horses, there’s a range in the cost per horse. Often, these expenses are the lowest per horse compared with the other expenses listed previously.
After establishing some monthly income vs. expense data, you’ll see what it costs you to shoe a horse and what your profit might be. Your expenses may total approximately one-third of your gross income. However, the sad part comes next — taxes! Some states do not have income taxes, but everyone must pay federal income and Social Security taxes. The magic word here is: tax-deductible. This all goes on your Schedule C, the profit and loss statement.
To reduce your tax obligation further, contributions to an Individual Retirement Account — IRA — or other tax-deductible or deferred retirement accounts are essential. Home mortgage interest and real estate taxes are ways to reduce your tax burden and keep more of what you earn. Always consult a tax specialist to file this information properly.